 When a homeowner decides to buy a home he or she must obtain the finances to pay for the home. The homeowner usually goes to a financial institution, submits an application and if they are approved they receive a loan. There are two (2) parts to the loan them receive. The first part is a note.
The Note
The note is a written agreement that the financial institution is lending a homeowner money and it contains the homeowner’s agreement to repay the money. The note includes the terms and conditions of the repayment: such as whether the note is to be repaid in 15 years or 30 years. It also includes the rate of interest charged on the loan and the late charges, fees and expenses. In simple terms, a note is an IOU.
The Mortgage
The mortgage is a contract that gives the financial institution, lender, a lien on real property. In simple terms, the home is the collateral that secures the note for the financial institution. The terms of the mortgage spell out what the financial institution can do should the requirements of repayment in the note and mortgage are not met by the homeowner. What the mortgage lender usually does is they foreclose on the mortgage for the homeowner’s failure to make the timely, monthly payments required by the note.
 The law firm of Schlissel DeCorpo LLP has been helping families deal with mortgage and foreclosure problems for more than 30 years. We can be reached at 718-350-2802, 516-561-6645 or 631-319-8262 or by e-mail at info@sdnylaw.com.
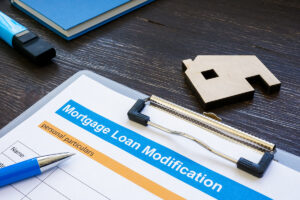 Obtaining a loan modification is one of the potential routes to save a home from the foreclosure process. There was a time in New York, and in the United States, when there were a variety of Federal and State programs which helped homeowners who had fallen behind in their mortgage due to unforeseen financial circumstances or other issues which caused them to fall behind on their mortgage payments. However, except for programs that help veterans, there are very few options today regarding mortgage modifications other than dealing with the financial institution which currently holds the mortgage on the homeowners’ homes.
 The State of New York has a law which states in all
 Life is not static. A families financial situations can change related to loss of employment, downsizing employment, financial tragedies, health issues, marital problems and many other issues. When a family falls


